
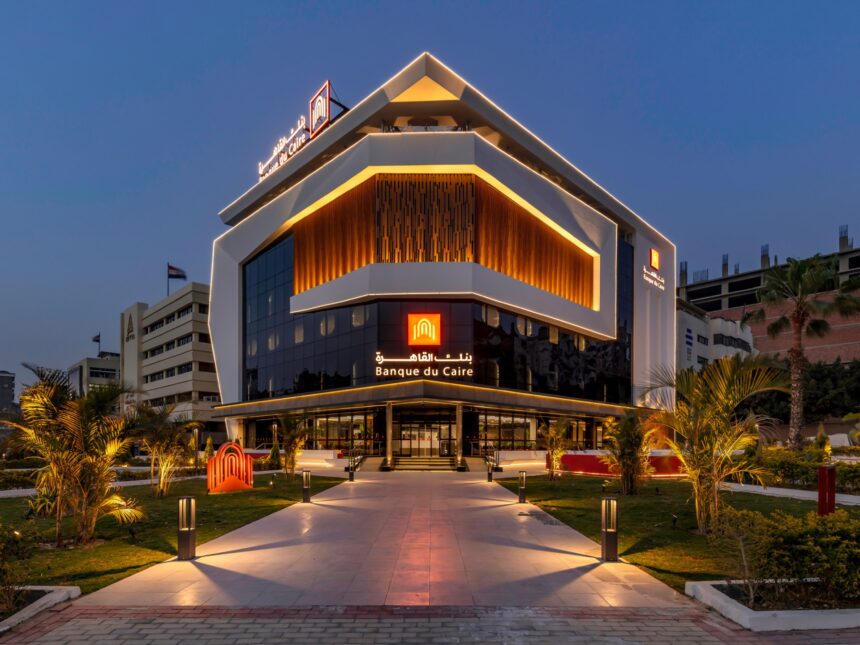
Banque du Caire delivered solid financial performance during the first nine months of 2026, supported by robust core profitability, healthy business growth, an improving funding mix and a strong capital position.
The bank’s consolidated net profit increased by approximately 19% after excluding the impact of three non-recurring income items recognised during the comparative period in 2025.
Net profit
The bank recorded consolidated net profit of EGP 13.1bn during the first nine months of 2026, compared to EGP 11.06bn in the corresponding period of 2025. Excluding the impact of three non-recurring income items recognised during the comparative period, net profit growth reached approximately 19%.
These items comprised income generated from an interest-free subordinated loan, which was repaid in December 2025; dividend income from the bank’s investment in the African Export-Import Bank (Afreximbank), which was subsequently sold; and foreign exchange gains associated with this foreign currency-denominated investment.
Profit before tax reached EGP 19.2bn, compared to EGP 15.9bn in the same period of the previous year, representing an increase of 20.9%.
Total operating income
Consolidated total operating income increased by 16.2% during the first nine months of 2026 to EGP 34.6bn, compared to EGP 29.74bn in the corresponding period of 2025. This growth was driven by a 14.8% increase in net interest income and a 13.0% rise in net fee and commission income.
Core revenues, comprising net interest income and net fee and commission income, rose by 14.5% to EGP 33.7bn.
Administrative expenses increased by 18.0% to EGP 12.4bn, reflecting continued investment in core banking modernisation and digital transformation. The cost-to-income ratio stood at 36.0%.
Total assets
Consolidated total assets increased by 11.2% to EGP 600.9bn as of September 30, 2026, compared to EGP 540.4bn at the end of December 2025. Assets also grew by 7.1% compared to the end of June 2026.
Customer deposits increased by 17.0%, or approximately EGP 69bn, to EGP 473.5bn, representing quarter-on-quarter growth of 6.7%. Retail customers accounted for 74% of the deposit base, while the current account and savings account (CASA) ratio improved by 130 basis points to 52.7%.
Gross loans to customers and banks rose by 11.3% to EGP 287.4bn, representing quarter-on-quarter growth of 2.5%. Corporate lending increased by 12.0%, while retail lending grew by 10.2%. The gross loan-to-deposit ratio stood at 60.7%.
Total equity, including non-controlling interests, increased by 12.3% to EGP 70.3bn.
Asset quality and capital adequacy
Asset quality remained sound, with the non-performing loan (NPL) ratio standing at 3.70% and the provision coverage ratio reaching 173.1% as of September 30, 2026.
On a standalone basis, the adjusted NPL ratio, excluding loans granted before 2020, stood at 2.49%.
Expected credit loss charges declined by 44.0% to EGP 2.1bn, compared to EGP 3.8bn in the corresponding period of the previous year. The cost of risk also improved to 1.03%, compared to 2.09% in the first nine months of 2025.
The bank maintained a strong capital base, with a capital adequacy ratio of 22.15% and a Tier 1 capital ratio of 18.73%.
Its liquidity position also remained strong, with a liquidity coverage ratio of 759.0% and a net stable funding ratio of 177.3%, both on a standalone basis.
Meanwhile, annualised return on average equity stood at 26.3%, while annualised return on average assets reached 3.1%. Net interest margin stood at 7.2%.
Third-quarter performance
During the third quarter of 2026, consolidated operating income increased by 2.2% quarter on quarter to EGP 11.8bn, while core revenues rose by 1.7% to EGP 11.5bn.
Net profit declined by 13.1% to EGP 4.2bn, compared to EGP 4.8bn in the second quarter of 2026. This was mainly attributable to higher expected credit loss charges, which reached EGP 1.1bn, compared to EGP 489m in the previous quarter, alongside other expenses of EGP 231m, compared to other income of EGP 115m in Q2 2026.


