
The Housing and Development Bank (HDB) reported standalone profit before income tax and provisions of EGP 20.951bn in the third quarter (Q3) of 2026, compared to EGP 18.525bn in the corresponding period of 2025, marking an increase of EGP 2.426bn, or 13.15%.
The bank’s net profit after tax rose to EGP 14.843bn, compared to EGP 13.439bn in the same period last year, an increase of EGP 1.404bn, representing year-on-year growth of 10.4%.
Strong financial and operational performance
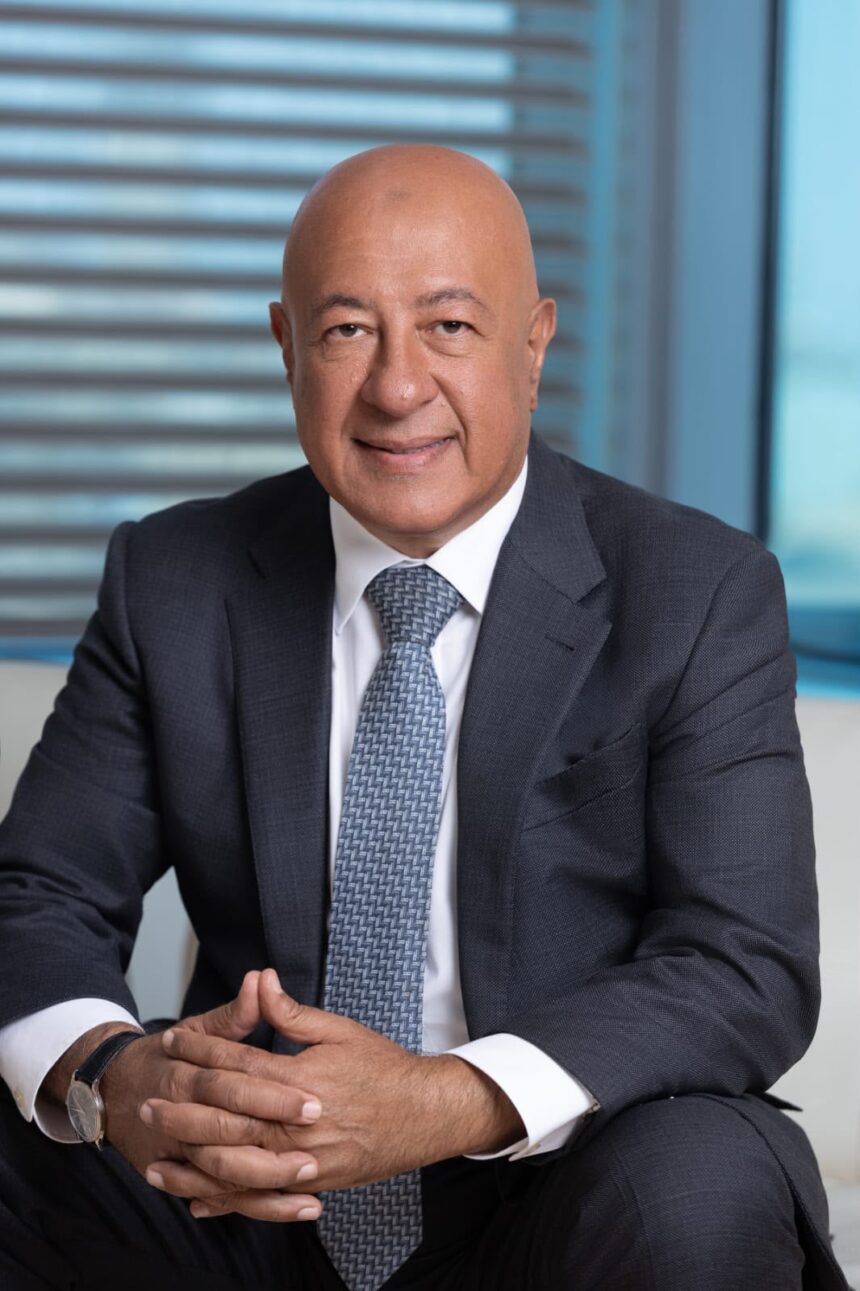
Yehia Abu El-Fotouh, CEO and Managing Director of HDB, said the bank continued to deliver strong financial and operational results during the nine months ending September 2026. He attributed the performance to the strength of its banking business model, operational efficiency and ability to achieve sustainable growth and profitability.
He added that the results were supported by the resilience of the bank’s financial position, efficient deployment of resources and assets, diversified income streams and expanding activities across various banking sectors.
Abu El-Fotouh explained that the performance also demonstrates the bank’s success in implementing its ambitious strategy and consolidating its position in the banking market by maintaining a balance between growth, profitability and liquidity, improving asset management efficiency, and pursuing measured expansion in its banking and financing activities.
He noted that the results build on the bank’s established track record and reflect its strong institutional legacy, well-established brand, growing customer confidence, accumulated banking and institutional expertise, distinguished human capital and operational capabilities, as well as its leading position in mortgage finance. These strengths underpin its ability to sustain growth and enhance its competitiveness in the banking market.
Banking activity
Regarding banking activity, HDB’s net interest income reached EGP 23.282bn, compared to EGP 20.280bn in the corresponding period of 2025, marking an increase of EGP 3.002bn, or 14.8%. This was driven by a 14.5% increase in returns on loans and similar income, alongside a 13.9% rise in the cost of deposits and similar expenses.
Net operating income also increased to EGP 25.350bn, compared to EGP 21.905bn, representing growth of 15.7% and reflecting the strength of the bank’s banking activities and operational efficiency.
In terms of profitability indicators, return on average equity, including the period’s net profit, stood at 47.57%, while return on average assets reached 7.79%, reflecting the efficient deployment of capital and the bank’s ability to maximise shareholder value.
Strong financial position
Regarding its financial position, HDB’s total assets increased to EGP 279.811bn in September 2026, compared to EGP 229.804bn in December 2025, an increase of EGP 50.007bn, or 21.8%. This reflects the expansion of the bank’s business and the efficient management of its financial resources.
The bank’s loan portfolio also grew to EGP 87.930bn in September 2026, compared to EGP 65.717bn at year-end 2025, representing an increase of 33.8%.
The corporate and institutional loan portfolio reached EGP 49.071bn, compared to EGP 32.784bn, marking growth of 49.7%. Meanwhile, the retail loan portfolio stood at EGP 38.859bn, compared to EGP 32.933bn, representing an increase of 18%. This reflects the bank’s expansion across various financing activities and its ability to meet the needs of diverse customer segments.
Total customer deposits increased to EGP 219.138bn in September 2026, compared to EGP 179.128bn at year-end 2025, an increase of EGP 40.010bn, or 22.3%.
Institutional deposits reached EGP 110.906bn, representing growth of 48.1%, while retail customer deposits stood at EGP 108.232bn, recording growth of 3.8%. These figures reflect customer confidence in the bank, its expanding deposit base and its ability to diversify funding sources.
Expanding the bank’s business base
The simultaneous growth in assets, loans and deposits underscores the expansion of HDB’s business base and strengthens its capacity to finance various economic sectors while maintaining a strong financial position and robust capital indicators.
As part of its efforts to maintain a strong financial position and capital base, the bank’s capital adequacy ratio stood at 45.28%, with the Tier 1 capital ratio reaching 44.17% and the Tier 2 capital ratio standing at 1.11%.
The loan-to-deposit ratio reached 40.1% in September 2026, compared to 36.7% at year-end 2025, reflecting the bank’s ability to support credit expansion while maintaining strong liquidity levels and effective risk management.
At the consolidated level, including the bank and its subsidiaries and affiliated companies, net profit after tax increased to EGP 16.241bn in September 2026, compared to EGP 14.454bn in the corresponding period of 2025, an increase of EGP 1.787bn, or 12.4%.
Non-performing loans
Regarding asset quality, HDB reduced its non-performing loan (NPL) ratio to 3.86% in September 2026, compared to 4.99% at year-end 2025. The provision coverage ratio for non-performing loans reached 178.8%.
These figures reflect the efficiency of the bank’s credit and risk management policies and its commitment to maintaining the quality of its loan portfolio. They also demonstrate its ability to balance credit expansion with asset quality through disciplined lending policies and an effective risk management framework.
Sustainable finance
As part of its commitment to integrating sustainability principles into its financing activities, HDB’s total funding allocated to sustainable projects reached EGP 19.6bn in the third quarter of 2026, representing year-on-year growth of 85.5%.
Meanwhile, the sustainable finance portfolio stood at EGP 12.7bn, recording growth of 83.5% compared to the corresponding period of 2025. This underscores the bank’s role in supporting projects that contribute to sustainable development and generate positive economic and social impact.
Diversifying sources of income
Abu El-Fotouh said the bank continues to implement a strategy aimed at diversifying income sources and increasing its market share. This involves developing a wide range of banking products and services, deepening customer relationships, attracting new customer segments, improving operational efficiency, fostering innovation and continuous development, and making effective use of available resources and capabilities. These efforts are intended to strengthen the bank’s profitability and support sustainable financial growth.
He noted that HDB aims to build on its achievements and further strengthen its competitive position, reinforcing its standing among the most efficient and competitive banking institutions. This will be pursued through an advanced banking model that combines strong financial performance, operational efficiency, innovation and a customer-focused approach.
Abu El-Fotouh added that over the coming months, the bank will continue to develop its business model, expand its innovative banking solutions and maximise added value for both customers and shareholders.


