
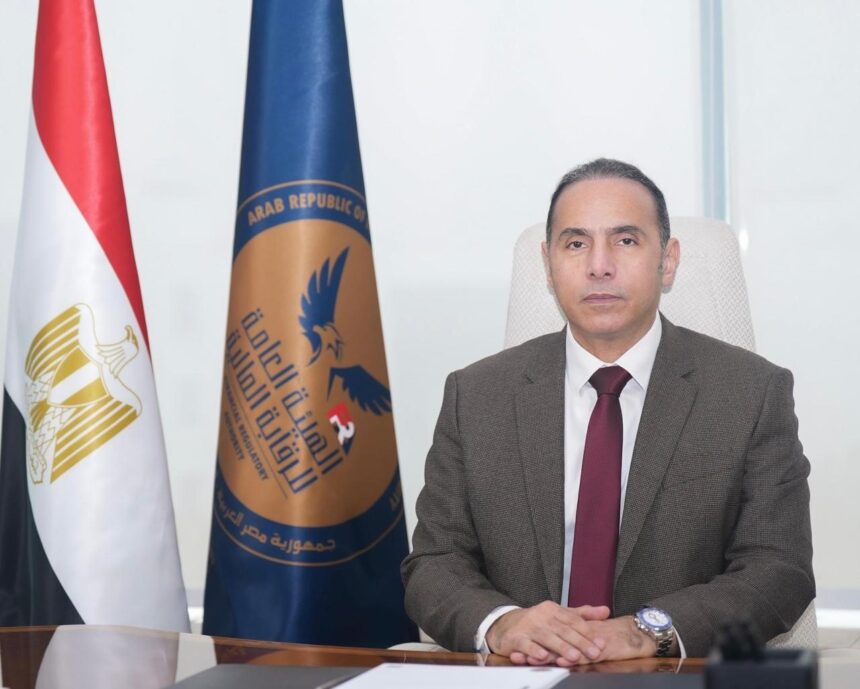
The Financial Regulatory Authority (FRA), chaired by Islam Azzam, has issued standard contracts governing the relationship between consumer finance companies and their customers, clearly defining the rights and obligations of both parties and addressing a range of contractual and practical issues that have emerged as the sector continues to expand.
The move forms part of the FRA’s ongoing efforts to strengthen market stability and facilitate compliance with the regulations governing non-banking financial activities.
The decision introduces two standard contracts: one covering consumer finance arrangements for the purchase of multiple goods or services, and another for financing a single purchase.
Companies are required to adopt these two templates in place of the contracts approved by the FRA in 2021, following the enactment of Consumer Finance Law No. 18 of 2020. They have been given a three-month period to comply with the new requirements.
Azzam said the decision introduces several updates to keep pace with market developments, striking a balance between supporting the growth of the sector and its companies and ensuring the highest possible level of protection for customers’ rights.
He explained that consumer finance companies must use the two standard contracts attached to the decision when entering into agreements with customers, whether financing multiple goods and services or a single transaction.
This requirement does not affect the other obligations imposed on companies operating under Fintech Law No. 5 of 2022, which regulates the use of financial technology in non-banking financial activities.
Azzam added that all mandatory information required under the contracts must be completed digitally, while contractual clauses must be drafted in clear and legible language.
Companies must also give customers an opportunity to review their contracts before signing and make a digital copy available through the relevant electronic application.
He explained that companies may include additional provisions beyond those contained in the standard contracts, provided they obtain the FRA’s prior no-objection approval for the proposed clauses.
Azzam stressed that companies must uphold the principles of honesty and integrity when providing services to customers and refrain from any conduct that could constitute mistreatment, particularly during the collection of outstanding payments.
Companies must also inform customers of the identities and contact details of debt collectors.
In turn, customers are required to ensure that the information they provide is accurate and complete, use financing exclusively for its agreed purpose, and make repayments on the agreed dates.
Azzam noted that the decision sets out these mutual obligations in clear and explicit terms.
The new standard consumer finance contract comprises 19 clauses, beginning with essential information about the company and the customer.
It also stipulates that both parties must comply with the relevant legislation, as well as the decisions and instructions issued by the FRA to regulate consumer finance activities.


